You could win £10,000!
Simply download, register and use the Scottish Widows app between 7 July and 31 December 2026. For full details and eligibility, or to opt out, see our terms and conditions.
Support
You could win £10,000!
Simply download, register and use the Scottish Widows app between 7 July and 31 December 2026. For full details and eligibility, or to opt out, see our terms and conditions.
Download the app
You could win £10,000!
Simply download, register and use the Scottish Widows app between 7 July and 31 December 2026. For full details and eligibility, or to opt out, see our terms and conditions.
Pensions
Investing
Investing Edge
From market updates to investment ideas, explore expert insights designed to help every investor make smarter decisions.
Know More. Invest Better.
Life insurance
Compare products
Learn more about our products and find the right one for you.
Scottish Widows Bank
Planning
Compare products
Learn more about our products and find the right one for you.
The Chancellor's Budget on 28 October 2026 included a number of important announcements. Our experts have taken a closer look at what was announced.
From the wider measures to the detail worth knowing, we’ve brought together some of the key changes in one clear summary.
The information on this page is an overview only and doesn’t cover all announcements made in the Budget.
Cash ISA allowance to remain at £20,000
The annual cash ISA allowance will remain at £20,000 from 06 April 2027. Savers can continue to contribute up to £20,000 each tax year, into cash ISAs, stocks and shares ISAs, or a combination of both.
The proposed stocks & shares ISA changes will also not go ahead, including the 22% charge on interest on cash held, restrictions on Money Market Funds and transfers into cash ISAs.
Changes to tax rates on income from property and savings
The Chancellor has announced further increases to tax rates on income from property and savings. From 06 April 2027, the basic, higher and additional rates of Income Tax on savings income will be 24%, 44% and 49% respectively across the UK. The same rates will apply to property income in England, Wales and Northern Ireland.
Changes to the Lifetime ISA
The government plans to replace the Lifetime ISA with a new First Time Buyer ISA for new savers from April 2029.
The new account will allow annual contributions of up to £4,000, with a 25% government bonus paid towards a qualifying first home purchase. Existing Lifetime ISA holders will be able to continue using their accounts.
From 29 October 2026, the withdrawal charge for Lifetime ISA holders purchasing a first home above the £450,000 property price cap will also fall from 25% to 20%.
A proposed incentive for first time investors
The government plans to work with the investment industry on a new incentive for people investing in a stocks and shares ISA for the first time. The features of the incentive and its implementation timetable have not yet been confirmed.

Cash ISA allowance to remain at £20,000
The annual cash ISA allowance will remain at £20,000 from 06 April 2027. Savers can continue to contribute up to £20,000 each tax year, into cash ISAs, stocks and shares ISAs, or a combination of both.
The proposed stocks & shares ISA changes will also not go ahead, including the 22% charge on interest on cash held, restrictions on Money Market Funds and transfers into cash ISAs.
Changes to tax rates on income from property and savings
The Chancellor has announced further increases to tax rates on income from property and savings. From 06 April 2027, the basic, higher and additional rates of Income Tax on savings income will be 24%, 44% and 49% respectively across the UK. The same rates will apply to property income in England, Wales and Northern Ireland.
Changes to the Lifetime ISA
The government plans to replace the Lifetime ISA with a new First Time Buyer ISA for new savers from April 2029.
The new account will allow annual contributions of up to £4,000, with a 25% government bonus paid towards a qualifying first home purchase. Existing Lifetime ISA holders will be able to continue using their accounts.
From 29 October 2026, the withdrawal charge for Lifetime ISA holders purchasing a first home above the £450,000 property price cap will also fall from 25% to 20%.
A proposed incentive for first time investors
The government plans to work with the investment industry on a new incentive for people investing in a stocks and shares ISA for the first time. The features of the incentive and its implementation timetable have not yet been confirmed.
Household energy bills
The Budget includes a £100 payment for up to 20 million households in council tax bands A to D in England from January 2027. Funding will also be provided to the devolved governments.
The temporary 0% VAT rate on domestic electricity will be extended to July 2027.
The government has also asked Ofgem to remove standing charges from household gas bills by the end of 2027, or as soon as possible afterwards.

Household energy bills
The Budget includes a £100 payment for up to 20 million households in council tax bands A to D in England from January 2027. Funding will also be provided to the devolved governments.
The temporary 0% VAT rate on domestic electricity will be extended to July 2027.
The government has also asked Ofgem to remove standing charges from household gas bills by the end of 2027, or as soon as possible afterwards.
A new tax allowance for people relying on the State Pension
The government has confirmed details of a new Pension Tax Allowance for pensioners relying on the State Pension.
From April 2027, pensioners whose total income is no higher than the full new State Pension will be protected from paying Income Tax simply because the State Pension has risen above the £12,570 Personal Allowance. The full new State Pension is due to rise to around £13,036 a year.

A new tax allowance for people relying on the State Pension
The government has confirmed details of a new Pension Tax Allowance for pensioners relying on the State Pension.
From April 2027, pensioners whose total income is no higher than the full new State Pension will be protected from paying Income Tax simply because the State Pension has risen above the £12,570 Personal Allowance. The full new State Pension is due to rise to around £13,036 a year.
Minimum wage
From 01 April 2027, the National Living Wage will increase by 3.9% to £13.21 an hour. National Minimum Wage rates will also rise by 3.9% to £11.27 an hour for 18 to 20 year olds and £8.31 for 16 to 17 year olds and eligible apprentices.

Minimum wage
From 01 April 2027, the National Living Wage will increase by 3.9% to £13.21 an hour. National Minimum Wage rates will also rise by 3.9% to £11.27 an hour for 18 to 20 year olds and £8.31 for 16 to 17 year olds and eligible apprentices.
Fuel
The government will extend the 5p cut in fuel duty for a further six months to 01 July 2027. The government is also deferring the planned Retail Prices Index inflation increase to 01 July 2027.

Fuel
The government will extend the 5p cut in fuel duty for a further six months to 01 July 2027. The government is also deferring the planned Retail Prices Index inflation increase to 01 July 2027.
What could the Autumn Budget mean for you and your financial plans?
Scottish Widows works with Lloyds Wealth to give customers access to financial advice and support when they need it. Their panel of experts looks beyond the headlines to discuss the key announcements, the economic and investment outlook, and some of the practical considerations for the months and years ahead.
If you have questions about what the Budget could mean for your finances, Lloyds Wealth can help you understand your options.
You can start with a free conversation to discuss your goals and explore your options. Experts can help build you a personalised financial plan at no initial cost. You’ll only pay if you choose to proceed with their recommendations.
To use the service, you should currently have:
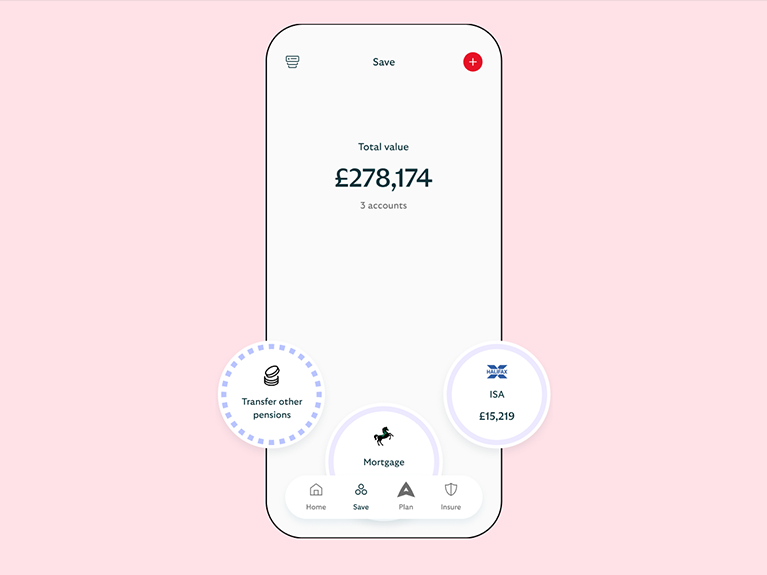
The Scottish Widows app makes it easy to see the total value of all your pensions and investments in one place, even if they’re not with us.
You can also add all your insurance policies, and see where there might be gaps in your cover.
The Scottish Widows app makes it easy to see the total value of all your pensions and investments in one place, even if they’re not with us.
You can also add all your insurance policies, and see where there might be gaps in your cover.
Find full details of the 2026 Budget (PDF, 5MB) on the government website.
Important information - this page is for information purposes only. It is not intended as investment advice and does not cover all announcements made in the 2026 Budget. On this page we refer to the tax rates and thresholds set for England and Northern Ireland, these may differ for the devolved nations of Scotland and Wales.
If you would like to discuss any of the topics covered here, including what is the best course of action for your individual circumstances, contact your financial adviser. If you don’t have an adviser you can find one at www.unbiased.co.uk An adviser will normally charge for advice.
Tax treatment depends on individual circumstances and may change in the future.
Lloyds Wealth is a trading name of Lloyds Wealth Management Limited.